
Last updated: September 2026
The Group sets out “Responding to climate change” as one of its materiality issues and promotes “Reduction of fossil-derived CO₂ emissions” and “Product development to improve environmental performance” as its sub-issues. Accordingly, we conduct a scenario analysis based on internationally recommended guidance. As a result, we recognize the importance of promoting initiatives to achieve carbon neutrality as part of the Group’s medium- to long-term strategy for addressing climate change-related risks and opportunities. We have declared our commitment to “Carbon Neutrality by 2050,” with the goal of achieving carbon neutrality by 2050 based on Scope 1 CO₂ emissions (direct emissions from the Company’s operations) and Scope 2 CO₂ emissions (indirect emissions associated with purchased and used energy, such as electricity, heat and steam), as indicators.
Governance on Climate Change
With regard to governance on climate change, the ESG Promotion Office, serving as the secretariat, coordinates with the organizations in charge to conduct scenario analysis, identify risks and opportunities, and discuss initiatives to realize carbon neutrality. With the ESG Promotion Office serving as the secretariat and in accordance with the Act on Rationalization of Energy Use and Shift to Non-fossil Energy and the Act on Promotion of Global Warming Countermeasures, the Environmental Promotion Committee, as an organization to ensure compliance with laws and regulations, meets once every six months to manage progress according to the plan. In FY2024, the ESG Promotion Office reported these environment-related activities, including CO₂ reduction, to the Board of Directors.
From FY2025, the Sustainability Committee discusses climate change-related risks and opportunities, manages the status of related initiatives, and makes recommendations based on the results to the Management Committee. Proposals related to climate change discussed by the Management Committee are reflected in the management plans of the Company’s business departments and Group companies through the Sustainability Committee.
Strategy for Achieving Carbon Neutrality
We have conducted an analytical assessment of the business risks and opportunities arising from climate change against projected changes in the environment from 2021 to 2040, using a scenario analysis approach based on internationally recommended guidance. As a result, we recognize promoting initiatives to realize carbon neutrality as a key issue, as the Group’s medium- to long-term strategy for risks related to climate change, and have declared “Carbon Neutrality by 2050,” which represents our aim to realize carbon neutrality by 2050, with Scope 1 and Scope 2 CO₂ emissions as indicators. An overview of the scenario analysis is provided below.
Scenario Analysis Overview
|
Scope of coverage |
Group consolidated companies (excluding the Bed and Furniture business) |
|---|---|
|
Time horizon |
2021–2040 |
|
Scenario development |
|
Assumed Changes in the Business Environment Related to Climate Change
【1】Assumed changes in the business environment in the 1.5°C scenario (mitigation of climate change)
The 1.5°C scenario assumes that, in around 2040, average temperatures may rise about 1°C above the current level, wind and rain from typhoons and low-pressure systems may intensify, and floods may occur about twice as frequently. It is assumed that government investment may increase in response to the intensifying wind and flood damage and that companies may be required to meet more stringent standards for reducing CO₂ emissions. The use of internal combustion engines that use fossil fuels may decline, with a shift to vehicles that use electricity and a growing presence of new entrants other than existing automakers, as the global response to climate change progresses. In that case, customers are likely to place fewer orders for products for internal combustion engines that use fossil resources and more orders for parts required for vehicles that use electricity, as well as for products designed and manufactured on the premise of reducing environmental impacts. In addition, there is a possibility that the growing environmental awareness of automobile end-users may lead to a shift from car ownership to car sharing, which may reduce global automobile production.
There is a possibility that, in procurement and manufacturing, the introduction of a carbon tax may increase the procurement price of raw materials, and that the switch to raw materials such as recycled plastic and biomass plastic may increase in response to customer demand. The possibility of damage to supply chains and manufacturing facilities due to severe wind and flood damage may increase, which could result in ad hoc responses and operational shutdowns.
【2】Assumed changes in the business environment in the 4°C scenario (adaptation to climate change)
The 4°C scenario assumes that, in around 2040, average temperatures may rise about 2°C above the current level, wind and rain from typhoons and low-pressure systems may intensify, and floods may occur about four times more frequently. It is believed that government measures may be strengthened in response to increasingly severe wind and flood damage. Due to rising temperatures, the number of people transported to hospital for heat stroke may double, and mosquito-borne and other infectious diseases, which have been rare to date, may also increase.
There is a possibility that fossil resource prices and energy rates will rise. In addition, the frequency of damage to supply chains and manufacturing facilities due to severe wind and flood damage may increase, which could result in an increasing number of ad hoc responses and operational shutdowns.
Based on the scenario analysis above, assumed market risks, market/technology risks and acute risks, as well as market/product/service opportunities, that may have impacts on the Group’s operations were identified. As a strategy to realize carbon neutrality, initiatives corresponding to those risks and opportunities are implemented in a variety of ways in the ordinary course of business by the respective organizations in charge. Of those, important ones are described in “Initiatives, Indicators and Targets for Climate Change-related Risks and Opportunities” below.
Managing Risks and Opportunities Related to Climate Change
The ESG Promotion Office, serving as the secretariat, collaborated with the organizations in charge to identify business risks and opportunities that may arise from changes in the environment under the 1.5°C and 4°C scenarios and to examine their estimated degree of financial impact. As a result, assumed market risks, market/technology risks and acute risks that may have impacts on the Group’s operations were identified. Meanwhile, under the direction of the Risk Management Committee, which is responsible for managing the Group’s risk of losses, other organizations also analyze and examine climate change-related risks, including scoring their frequency of occurrence and amount of impact and formulating countermeasures. The Risk Management Committee comprehensively evaluates and manages the climate change-related risks reported by the organizations in charge.
At the same time, opportunities related to climate change are also identified through scenario analysis, with the ESG Promotion Office serving as the secretariat and collaborating with the organizations in charge to identify opportunities for markets, products and services, and the organizations in charge of responses taking action. From FY2025, sustainability opportunities are identified by the Sustainability Committee, which manages the status of initiatives and makes recommendations based on the results to the Management Committee. Sustainability opportunities discussed by the Management Committee are reflected in the management plans of the Company’s business departments and Group companies through the Sustainability Committee.
Risks considered to have a significant financial impact |
Expected timing |
Key response policies |
|
|---|---|---|---|
|
Market risk |
As electric vehicles become more widespread, functional parts related to structures unique to gasoline-powered vehicles, such as parts around conventional engines and fuel fillers, may gradually decrease. |
Medium to long term |
|
|
As more and more companies from other industries enter the automotive industry, mega-suppliers that have supplied other industries may become new competitors. |
Medium to long term |
|
|
|
A failure to respond promptly and appropriately to customer demand for the use of recycled raw materials (such as biomass plastics) could result in lower sales and higher procurement costs. |
Short to long term |
|
|
|
Market risk/ |
Nifco’s business with existing and emerging automakers may decrease due to the emergence of alternative products with lower CO₂ emissions. |
Short to long term |
|
|
Acute risk |
The likelihood of supply chain disruptions due to severe weather events, such as storms, snow and freezing temperatures, may increase, which could increase the cost of purchasing expensive materials and of transportation in order to avoid supply risks to customers caused by the resulting shortages of materials. |
Short to long term |
|
Opportunities considered to have a significant financial impact |
Expected timing |
Key response policies |
|
|---|---|---|---|
|
Market/ |
The rapid expansion of opportunities related to lighter vehicles, non-ICE vehicles and the use of renewable energy aimed at reducing CO₂ emissions may increase demand for specialized functional parts used in motors, battery packs, battery cells (including all-solid-state batteries) and braking systems. |
Short to long term |
|
Resilience in Mitigation of and Adaptation to Climate Change
As a result of analyzing our business under the two scenarios—the 1.5°C scenario, in which climate change is mitigated, and the 4°C scenario, in which climate change becomes more severe—issues with a relatively high degree of impact were identified in market, technology and acute risks. However, we consider that all of these risks can be avoided if we continuously monitor future market changes and make prompt decisions with respect to market and technology risks, and take advance measures against acute risks. We therefore judge that the Company has a certain degree of resilience to climate change.
Initiatives, Indicators and Targets for Climate Change-related Risks and Opportunities
【1】Important initiatives, indicators and targets for climate change-related risks and opportunities
Based on projected changes in the environment from 2021 to 2040, derived using a scenario analysis approach based on internationally recommended guidance, we narrowed down and examined climate change risk items with a significant impact from both financial and non-financial perspectives. For market risks, over the medium to long term, there is a possibility that as electric vehicles become more widespread, functional parts related to structures unique to gasoline-powered vehicles, such as parts around conventional engines and fuel fillers, may gradually decrease, and that as more and more companies from other industries enter the automotive industry, mega-suppliers that have supplied other industries may become new competitors. In terms of market/technology risks, there is a possibility that the Group’s business with existing and emerging automakers decreases due to the emergence of alternative products with lower CO₂ emissions. As for acute risks, there is a possibility that the likelihood of supply chain disruptions due to severe weather events, such as storms, snow and freezing temperatures, increases, which could increase the cost of purchasing expensive materials and of transportation in order to avoid supply risks to customers caused by the resulting shortages of materials. On the other hand, as opportunities for markets, products and services, we consider that the rapid expansion of opportunities related to lighter vehicles, electrified vehicles and the use of renewable energy aimed at reducing CO₂ emissions may increase demand for specialized functional parts used in motors, battery packs, battery cells (including all-solid-state batteries) and braking systems. Major initiatives for those risks and opportunities are implemented in a variety of ways in the ordinary course of business by the respective organizations in charge of responses. All indicators for those transition and physical risks, as well as opportunities associated with climate change, have been set internally and are already in use; however, given their importance to our business strategies, they are currently kept undisclosed. In the future, we will carefully consider the possibility of disclosing such information.
As another important initiative, in order to address the market risk that a failure to respond promptly and appropriately to market regulations and customer demand for the use of recycled raw materials could result in lower sales and higher procurement costs, we are promoting the use of non-fossil resource materials, recycled plastics and materials derived from natural resources (biomass), and developing product shapes and processing methods that satisfy the specifications of products incorporating recycled materials (including biomass plastics). We have also endorsed the Sustainable Plastics Initiative, participate in public-private-academic partnerships (the Ministry of the Environment and the Ministry of Economy, Trade and Industry) and collaborate with the Japan Auto Parts Industries Association, and take a leading role in driving the transition to a circular economy across the entire industry. These important initiatives are also linked to our materiality of “Resource Recycling Initiatives Aimed at Zero Waste Plastic.”
Through the “XtoCar Project,” which was selected in FY2024 as a publicly solicited project sponsored by the Japan Foundation for Advanced Auto Recycling (J-FAR), manufacturing and other production industries (upstream) and waste recycling and treatment industries (downstream) are working together toward establishing a new recycling system for converting waste plastic from non-automotive sources into automotive parts. We aim to mass-produce products for automobiles that use recycled materials in the future. In FY2025, we completed the selection of one type of waste plastic that can be applied to automobiles. In FY2026, we aim to apply it to medium-sized products and further expand the types of plastic that can be handled.
【2】Indicators and targets for realizing “Carbon Neutrality by 2050”
The Company has declared “Carbon Neutrality by 2050” as its medium- to long-term strategy to combat climate change. As primary indicators for reducing CO₂ emissions, for Scope 1 and Scope 2, we aim to reduce CO₂ emissions by 33% by 2030 compared with 2020 (the Company on a non-consolidated basis and its subsidiaries in Japan) and to achieve carbon neutrality by 2050.
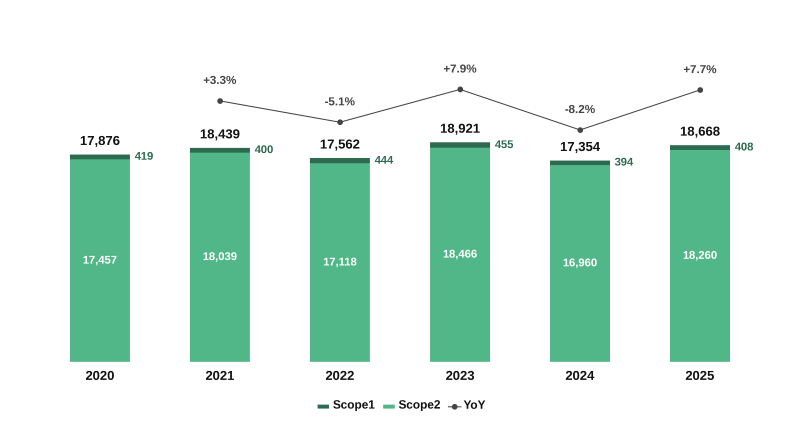
In FY2025, Scope 1 and Scope 2 emissions were 408 t-CO₂ and 18,260 t-CO₂, respectively (18,668 t-CO₂ in total). For the purposes of the climate change scenario analysis, these figures cover the Company on a non-consolidated basis and its subsidiaries in Japan (excluding Simmons). For the aggregation method, we adopt the GHG Protocol, which is the global standard calculation method.
At the Nagoya Plant, we commenced the supply of renewable energy in October 2025 through a supply-chain collaboration that utilizes the rooftop of a business partner’s distribution center, launching self-wheeling and the sale of surplus electricity generated by a 1.8 MW photovoltaic power facility, the largest of its kind in Japan's 60 Hz grid region. Through this initiative, we expect to reduce Scope 2 emissions by 6.2% (equivalent to 1,049 t-CO₂), when combined with existing facilities. The plant will continue to promote the introduction of renewable energy with the aim of becoming, at an early stage, a model plant that has achieved carbon neutrality.
Nifco Kitakanto also began self-consumption of electricity generated by an onsite photovoltaic power system in October 2025. The entire Nifco Group will continue to work to increase the ratio of renewable energy.
For Scope 3, the calculation is primarily based on the amount of orders in accordance with the GHG Protocol. Emissions in FY2025 amounted to 257,544 t-CO₂. This figure covers the Company in Japan on a non-consolidated basis. As the calculation is based on purchase order amounts, the figures may be influenced by fluctuations in exchange rates, material costs and transportation costs, which may result in variances from actual CO₂ emissions. We will improve the precision of calculation in stages by strengthening coordination with important affiliated companies.
Trends in Scope 1 and Scope 2 emissions
* Scope of coverage: the Company on a non-consolidated basis and its Group companies in Japan (excluding Simmons)
Trends in Scope 3 emissions
* Scope of coverage: the Company on a non-consolidated basis in Japan
We currently disclose emissions for Scope 1 and Scope 2 at the Company and its Group companies in Japan. Understanding and disclosing this information enables us to formulate action guidelines aimed at maintaining our competitive advantage. By identifying areas and processes with significant impacts within the Company and its Group companies in Japan, we can take proactive measures to address rising business costs resulting from tighter CO₂ emissions regulations and the introduction of carbon taxes, as well as increasing expectations from customers and business partners regarding decarbonization, and can clearly identify the need for renewable energy adoption, efficient capital investment and the development of new technologies. This strengthens the foundation for sustainable growth. At the same time, even though the scope is currently limited to Japan, we recognize that proactive disclosure of data serves as a means of gaining the trust of customers and investors who place importance on environmental responsibility, that it will lead to expanded business opportunities, and that it will contribute to future deployment across all consolidated companies.
At present, we do not officially disclose data from overseas sites due to concerns regarding data accuracy. However, with a view to improving data accuracy on a global basis and establishing a management framework robust enough to obtain third-party assurance, we began implementing an environmental data management system in FY2025. We will increase the number of sites where this system is installed in stages, and aim for centralized data management at all sites globally in the future.
In addition, with regard to the calculation of Scope 3, it is difficult at present to capture and calculate emissions in a uniform manner due to differences in data retention and management methods across the entire supply chain. For this reason, we disclose CO₂ emissions only for the Company. In the future, we will strengthen coordination with important affiliated companies and consider the preparation and disclosure of Scope 3 data in stages.
Although climate change-related risks and opportunities vary in their potential impact, the Company will continue to implement appropriate initiatives through its governance framework and risk and opportunity management processes in order to maximize corporate value.